

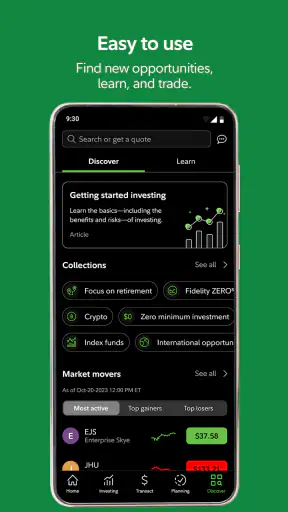
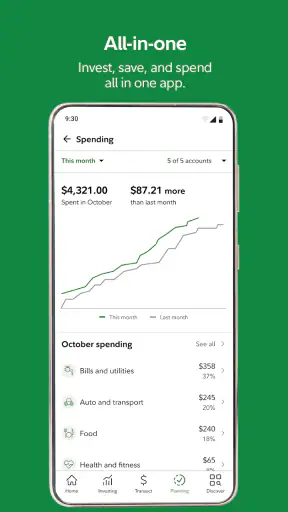
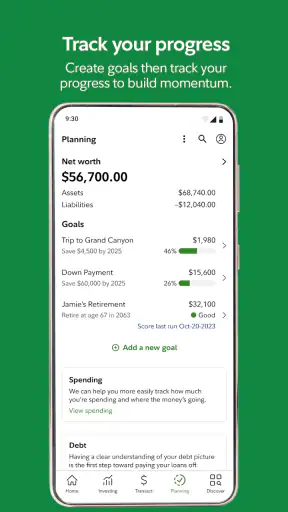
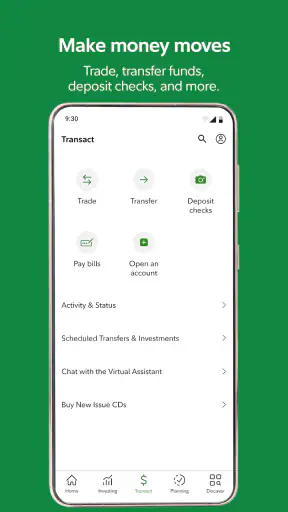
Managing investments from a phone sounds convenient until an app makes an important task feel slow, crowded, or difficult to verify. After spending time with Fidelity Investments, I found a finance app that aims to put investing, saving, and planning in one place without turning every screen into a trading terminal. That broad approach is its main appeal: it can support regular account checks, occasional trades, longer-term planning, and everyday money decisions from the same mobile experience.
It is a free app from Fidelity Investments, and its Everyone age rating makes it approachable for a wide range of users. The app has been available since December 15, 2010, which gives it a long history compared with many newer finance tools. Its current version is 4.39, and the scale of its audience is substantial, with more than five million installs, roughly 220 thousand ratings, and an average score of 4.1. Those figures suggest a mature product that many people use regularly, while also reminding me that a large user base does not automatically mean every investor will enjoy the same workflow.
How Fidelity Investments feels during ordinary use
The first thing I noticed is that this is not an app designed around only one financial habit. A minimalist investing app may be easier if you want to see a portfolio and place an occasional order, while a budgeting app may be better for tracking spending. Fidelity Investments sits between those experiences. It is built for people who want investment access alongside saving and planning tools, so the interface can feel more substantial than a single-purpose alternative.
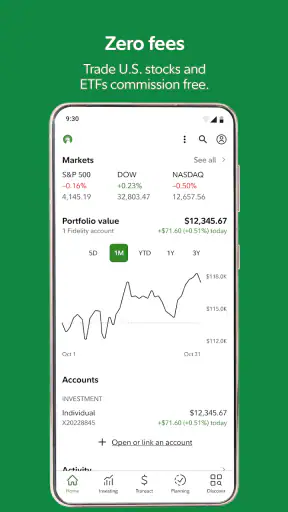
That extra breadth is useful when your financial life does not fit into one narrow category. I can imagine opening it to check a retirement account, reviewing available cash, looking at investment positions, and then moving into planning rather than switching between several unrelated apps. The trade-off is that a wider financial dashboard asks me to pay closer attention to where I am and what action I am about to take. For a beginner, the number of possible directions may feel less immediately obvious than a stripped-down investing app.
The best way to judge this app is by the decisions you want to make, not by how many screens it contains. If you need a central place for investing and planning, its scope is sensible. If you only want a quick market glance with no surrounding account context, it may feel heavier than necessary.
Speed expectations when checking an account
For routine use, I expect the app to feel most comfortable when I already know my destination: checking a balance, reviewing positions, or moving through a familiar planning area. Those tasks are naturally more manageable than exploring the whole product from scratch. The layout is easier to appreciate after I have established a personal routine, because repeated actions become less mentally demanding than the first tour through a broad finance app.
Finance apps also need to be judged differently from games or social feeds. A screen that takes a little longer to load is annoying, but an unclear confirmation or an easy-to-miss account detail is more serious. I would rather have a deliberate review step before a transaction than a design that feels instant but encourages careless taps. With Fidelity Investments, I treat speed as useful only when it does not reduce clarity around money.
One practical habit is to separate browsing from acting. I can open the app to review my situation, note what needs attention, and only then begin a transaction or account change. This reduces the chance of making a rushed decision while moving through several financial sections. It also makes occasional slowness less disruptive, because I am not trying to complete every task in a single hurried session.
What happens during heavier financial sessions
The app becomes more demanding when I use it for several purposes in one visit. A session might begin with a portfolio check, continue into planning, and end with a review of available funds or account activity. That kind of use is where the all-in-one design earns its place, but it is also where navigation can feel less lightweight than a specialist app.
For a long-term investor who checks in periodically, this is probably a reasonable trade. I do not need every visit to be instantaneous if the app helps me connect an account review with a larger plan. On the other hand, someone who watches markets closely and wants a highly focused trading workspace may prefer a tool designed around rapid research and execution rather than a wider financial relationship.
A useful workflow is to avoid opening the app with an undefined goal. Before launching it, I would decide whether I am checking progress, planning, reviewing cash, or preparing an investment action. That small distinction matters because the app covers several jobs. It keeps a broad dashboard from becoming a distraction and helps me notice when I am drifting from information gathering into a decision I did not intend to make.
Another non-obvious trade-off is that consolidation can improve awareness while increasing responsibility. Seeing more of my financial picture in one place may make it easier to spot a mismatch between short-term cash needs and long-term investing. But it can also tempt me to make changes simply because I am looking at the account. I would use the planning side to support a decision, not as a reason to constantly adjust a portfolio.
Reliability, stability, and recovering from interruptions
Reliability matters more here than visual polish. A finance app needs to leave me confident about which account I am viewing, what information has refreshed, and whether an action has actually completed. I do not consider a session successful merely because the interface opened quickly. The important question is whether I can finish a task without uncertainty.
When a connection is weak or a session is interrupted, I would not immediately repeat an important action. My safer routine is to return to the relevant account area, check the visible activity or status, and confirm what happened before trying again. This is especially important for transfers or investment actions, where tapping twice out of impatience can create confusion. The app can support the workflow, but careful recovery remains the user’s responsibility.
I also prefer using a stable connection for anything consequential. A brief interruption during browsing is usually manageable; an interruption while submitting a financial instruction deserves a pause and a verification step. That is not a criticism unique to Fidelity Investments, but the app’s broad financial role makes disciplined recovery particularly important.
Its long presence in the mobile finance space is reassuring in one limited sense: this is not an experimental newcomer built around a short-lived idea. Still, longevity should not be confused with a guarantee that every release or device behaves perfectly. I would keep the app updated through the normal platform process and maintain a habit of checking account activity directly after important actions.
Device limits and everyday practicality
Because the app handles several financial jobs, the experience depends partly on how comfortable I am reading detailed information on my phone. A larger screen can make account summaries, planning views, and investment details easier to scan. On a smaller display, I would expect to spend more time scrolling and checking labels before acting. That does not make the app unsuitable for a compact phone, but it does make focused sessions more appealing than trying to review everything at once.
Resource demands are also best understood through the type of work being done. A quick balance check should feel like a lighter task than a long session moving among multiple account and planning areas. I would avoid keeping the app open unnecessarily while performing unrelated activities, especially on an older device where switching between demanding apps may be less comfortable. The practical test is not whether it consumes fewer resources than every alternative, but whether it remains responsive enough for the financial tasks I actually perform.
For someone using an older phone, I would start with simple account checks before relying on it for a more involved routine. If screens take too long to become usable, text is difficult to read, or returning from another app repeatedly disrupts the session, a desktop browser or a simpler finance app may be a better complement. Fidelity Investments is most useful when the device lets me review information carefully rather than forcing me to rush through a cramped interface.
Who will get the most value from it
I see the strongest fit for an investor who wants one established mobile home for investing, saving, and planning. It is particularly appealing when the goal is continuity: reviewing accounts in the same place, thinking about longer-term objectives, and making occasional decisions without maintaining several disconnected tools.
Consider a realistic weekday scenario. I might open the app after receiving income, check how much cash is available, review whether my investment accounts still match my intended plan, and then leave without making a trade. On another day, I could use the planning side to think through a future goal rather than reacting to a short-term market movement. The value is not just convenience; it is the chance to connect a small money check with a broader financial habit.
It can also suit someone who is moving beyond a basic savings account and wants a clearer view of investing without immediately adopting a specialized trading setup. The app’s broad design gives that person room to grow. At the same time, I would not mistake a comprehensive interface for personal financial advice. The app can organize information and actions, but I still need to understand what I am choosing and whether it fits my circumstances.
Who should choose a different option
I would hesitate to recommend it to someone who wants only a very simple spending tracker. The app’s focus is broader than recording daily purchases, so a dedicated budgeting tool may provide a cleaner experience for that specific job. Likewise, a person who wants a highly visual, beginner-first investing interface may prefer an alternative that hides more complexity and presents fewer account categories.
It may also be a less comfortable choice for an active trader who values a specialized workspace above all else. A focused trading platform can be preferable when research, rapid monitoring, and order-oriented navigation are the main priorities. Fidelity Investments makes more sense when investing is part of a wider financial picture rather than the only reason for opening the app.
That distinction answers an important question: is it suitable for a complete beginner? My answer is yes, but with a measured approach. I would begin by learning the account layout and planning tools, then use small, clearly understood actions rather than exploring every option at once. Beginners who expect the app to make decisions for them should look elsewhere for education and personal guidance, because convenience does not remove the need for judgment.
Small habits that make the experience better
My first recommendation is to create a repeatable review order. I would start with the account or goal I intended to check, review the information needed for that purpose, and exit instead of wandering through unrelated sections. This makes the app feel faster because I spend less time searching, and it reduces the risk of acting on a passing impulse.
Second, I would use planning as a checkpoint before changing an investment approach. If the app presents both current account information and longer-term planning context, that combination is more useful than treating each screen separately. A sudden market change can make a portfolio look urgent even when the underlying goal has not changed. Reviewing the goal first can help me distinguish a real financial need from a temporary emotional reaction.
Third, I would confirm the outcome of any important action after the interface returns to a normal state. If the app closes, loses connection, or appears to stall, I would check the account activity before trying again. This recovery habit is more valuable than chasing the fastest possible tap sequence, and it applies especially well to a finance app where duplicate actions can be costly or confusing.
Finally, I would avoid judging performance from one isolated session. A phone’s age, connection quality, screen size, and the number of tasks in progress can all change how an app feels. I would test the workflow I actually need over several ordinary visits: a balance check, a planning review, and a carefully verified account action. That gives a more honest picture than a quick launch test.
My performance verdict after using the full experience
Fidelity Investments feels like a substantial finance app rather than a narrowly optimized utility. Its main strength is the way investing, saving, and planning can sit within one mobile routine. Its main weakness is the same breadth: users looking for a tiny, instantly understandable tool may find the experience more involved than necessary.
In terms of perceived speed, I would call it practical when I approach it with a clear task, not aggressively minimal. During heavier sessions, the wider set of financial activities can demand more attention and patience, but that is a fair exchange for users who value consolidation. Stability and recovery deserve a cautious workflow: verify important outcomes, avoid repeating an interrupted action, and use a reliable connection when money is involved.
The app is free, carries an Everyone rating, and comes from Fidelity Investments, a developer with a long-running presence behind this product. Its 4.1 average from around 220 thousand ratings and its audience of more than five million installs show that it has broad reach, while the roughly 58 thousand written reviews indicate substantial user discussion around the experience. I would treat those figures as context, not as a substitute for deciding whether its style matches my own financial habits.
I recommend it to people who want a single, mature mobile place to review investments and connect them with saving and planning. I would choose a simpler budgeting app for spending-only needs, or a more specialized trading tool for highly active market work. For everyone in between, the sensible approach is to use Fidelity Investments deliberately: open it with a purpose, separate reviewing from acting, and confirm every important result. Used that way, it becomes a useful financial workspace rather than just another app to check compulsively.


